
In a report sent to Rigzone by the Standard Chartered Bank team late Monday, the company’s Energy Research Head, Emily Ashford, outlined that there will be no return to normal for the oil market, warning that the “oil risk premium is becoming structural”.
Ashford revealed in the report that Standard Chartered Bank has raised its oil price forecasts “given stalled diplomacy and regional escalation beyond Iran and Hormuz”, noting that it sees “a structurally higher price floor as the energy system shifts from efficiency towards resilience”.
The Energy Research Head highlighted in the report that Standard Chartered Bank’s call rests on three “key developments”. The first of these is that the conflict is “regional rather than bilateral”, the second is that “diplomacy is increasingly likely to produce an imperfect and gradual de-escalation, rather than a clean reset”, and the third is that the energy system “is moving from optimization around efficiency towards resilience, redundancy, and optionality,” Ashford pointed out.
The report revealed that Standard Chartered Bank has raised its average Brent crude forecast for 2026 to $92.00 per barrel, from $85.50 per barrel, and its 2027 Brent crude forecast to $89.50 per barrel, from $77.50 per barrel. Standard Chartered Bank’s average WTI forecast for 2026 is now $86.00 per barrel, from $80.25 per barrel, and its 2027 WTI forecast has risen to $82.75 per barrel, from $72.50 per barrel, the report showed.
“The energy market is confronting a more persistent deterioration in the Middle East security environment,” Ashford said in the report.
“We see little prospect of a return to the pre-conflict status quo. No credible pathway to a durable settlement is yet visible and the conflict has now broadened to a regional security problem with the Houthi/Saudi escalation adding a second front,” Ashford added.
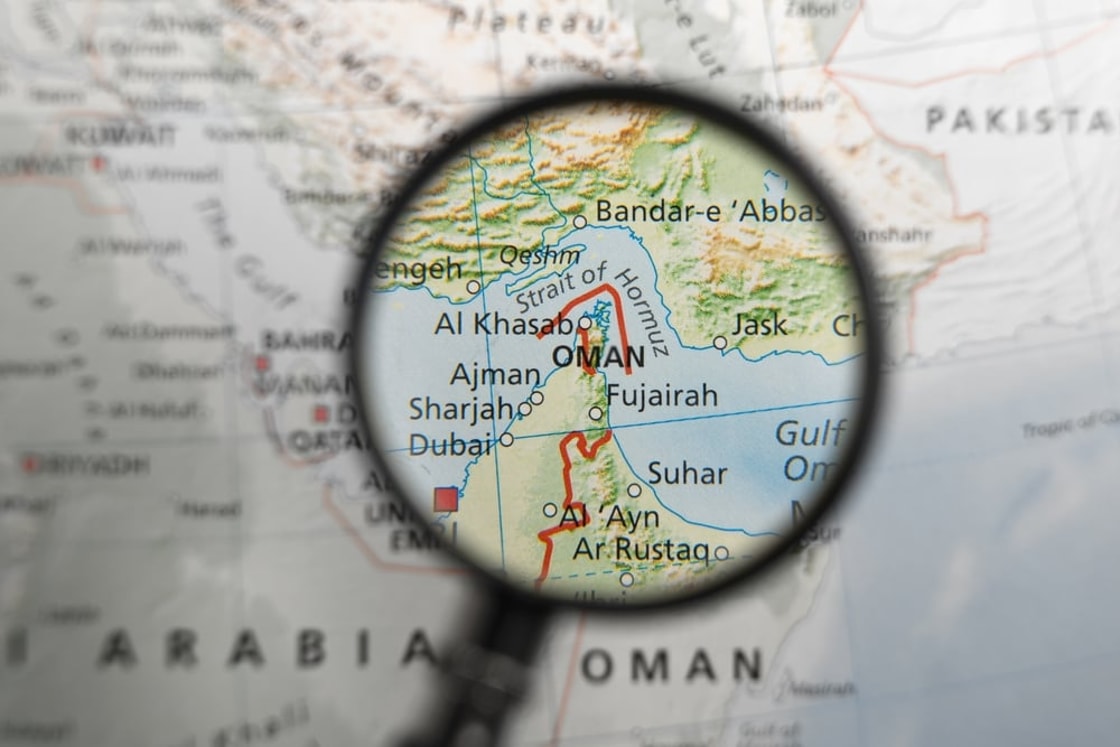
“This means that risk is no longer concentrated just around Iran and the Strait of Hormuz, and Saudi Arabia has been drawn deeper into the conflict,” Ashford warned.
Higher Price Threshold
In the report, Ashford noted that Standard Chartered Bank’s new oil price forecasts reflect a higher price threshold and warned that there is potentially lasting physical damage to the energy system.
“The key change in our forecasts is not simply a higher oil price, it is a higher threshold for what constitutes ‘normal’,” Ashford said.
“The conflict may eventually end, but we do not expect the risk architecture that has been exposed to disappear with it,” Ashford added.
“The longer the conflict remains in this impasse, the more difficult and expensive it becomes to return to the old equilibrium,” Ashford continued.
“The current disruption is more than a temporary supply shock. It is accelerating a structural shift supporting both a longer period of elevated oil prices and a higher long-term price floor,” Ashford went on to state.
The Energy Research Head pointed out in the report that the company raised its oil price forecasts in the short term because the current risk premium is proving more persistent than Standard Chartered Bank had previously assumed.
“The longer the impasse continues, the greater the potential damage to energy infrastructure and oil reservoirs, and the greater the depletion of strategic and commercial inventories,” Ashford warned.
“The U.S. Strategic Petroleum Reserve is approaching levels at which operational flexibility becomes increasingly constrained, and its ability to provide another buffer against prolonged disruption is diminishing,” Ashford added.
According to a data page on the U.S. Energy Information Administration’s (EIA) website, which displayed weekly U.S. ending stocks of crude oil in the SPR from August 1982 to September 2026, and was last updated on September 23, weekly ending stocks of crude oil in the SPR came in at 284.552 million barrels in the week ending September 18. The last time SPR stocks were lower than the September 18 figure was in the week ending October 29, 1982, when they came in at 284,268 million barrels, the data page showed.
Looking at 2027 in the Standard Chartered Bank report, Ashford outlined that the company’s higher forecasts reflect a slower normalization of flows and inventories than it had envisaged.
“We now expect the long-term Middle Eastern geopolitical picture to be characterized by extended periods of stability, punctuated by episodic escalations that are likely to maintain a level of risk in the market for Gulf-associated barrels,” Ashford said.
“Longer-term, the marginal cost of resilience is now higher, and the market is likely to carry more redundancy,” Ashford added.
No Clean Exit
Ashford projected in the report that, at present, the U.S.-Iran conflict has no clean exit.
“November is the next obvious inflection point for U.S.-Iran diplomacy,” Ashford said.
“President Trump has stated that he expects a deal after the midterm elections (3 November), although the economic cost of elevated fuel prices creates a clear incentive for Washington to attempt to contain the conflict ahead of the vote,” Ashford added.
“Even if negotiations begin in earnest after November’s vote, the core disputes over Iran’s nuclear program, sanctions, Hormuz transit, and regional security remain unresolved,” Ashford warned.
“We therefore see a greater risk of an extended period of ceasefires and partial agreements, punctuated by intermittent escalation,” Ashford highlighted.
The Energy Research Head went on to note that the U.S. midterm elections in November may be an inflection point for U.S.-Iran diplomacy, but not necessarily an end point.
“There is genuine political incentive for Washington to contain the conflict, particularly given the impact of energy prices on U.S. consumers and notable exposure to high diesel prices across key agriculture-focused swing states such as Iowa,” Ashford pointed out.
“Iran has demonstrated its ability to disrupt Hormuz, the Houthis have demonstrated their ability to threaten Saudi energy infrastructure and Bab el-Mandeb. Gulf producers have seen the vulnerability of alternative export routes, with bypasses becoming further chokepoints,” Ashford added.
“Fragile diplomacy has been complicated by the Yemen escalation. Even if a ceasefire removes some risk premium, it will not necessarily remove the risk,” Ashford continued.
Ashford went on to state that, for years, the energy system has been optimized for efficiency – “low inventories, lean supply chains, limited spare capacity, minimal redundancy, and just-in-time logistics”. The events of 2026, however, have “exposed the costs of that model”, Ashford said.
“In our view, the long-term consequence will be greater willingness to pay for security, diversity, and optionality, with higher inventories, more spare capacity, diversified logistics, more redundancy and a higher price floor for energy,” Ashford noted.
“Longer-term, we forecast a slower normalization process than previously expected because a diplomatic breakthrough does not immediately restore disrupted flows, shipping patterns, inventories or confidence,” Ashford continued.
“With producers, consumers and governments likely to place a greater value on resilience and optionality, we expect a higher price floor,” Ashford stated.
Oil Price Trends
In a report sent to Rigzone by the Skandinaviska Enskilda Banken AB (SEB) team on Tuesday, SEB Chief Commodities Analyst Bjarne Schieldrop highlighted that spot crude oil prices are at “very high levels”.
“The Brent 1M (November) contract yesterday traded between $103.76 – 108.83 per barrel before settling the day at $105.28 per barrel,” Schieldrop noted.
“This morning it is trading up 1.4 percent to $106.8 per barrel. That is not much of a price given that the ME crisis has been ongoing since 28 February,” he added.
“The Dated Brent spot price, however, settled yesterday at $123.78 per barrel and averaged $120.6 per barrel last week,” he pointed out.
“Even stronger were the individual North Sea spot crude prices where Johan Sverdrup crude averaged $144 per barrel from 21 to 24 September,” Schieldrop noted.
“Johan Castberg was said to have traded at a premium of $32 per barrel to the Dated Brent price last week which potentially would have placed it closer to $150 per barrel,” he continued.
In the report, Schieldrop outlined that crude oil prices have been on a “steady trend upwards” since they “bottomed out at around $70 per barrel in early July” following the “discharge of some 200 million barrels of crude, products, and liquids from the Persian Gulf during a two week MoU window”.
Schieldrop went on to note in the report that the oil market today is split apart in time, space, and molecules.
“Financial crude oil prices for November delivery are trading at $106 per barrel (Brent) and $93.3 per barrel (U.S. WTI) and $107/b (Oman),” he highlighted.
“But spot crude oil prices are much higher at $120-150 per barrel as described above. But consumers do not consume crude oil, they consume diesel and gasoline and other products,” he added, noting that diesel prices “are closer to $200 per barrel in ARA due to destruction of Russian refineries and locked-in refineries in the Persian Gulf”.
“Oil markets are very stressed with respect to products but not so stressed with respect to crude oil. But refineries are eager to pay up for crude deliveries right here and now so they can convert that crude to products and make a killing profit,” he noted.
“They are not willing to pay up for November crude deliveries in the same way as uncertainties on the Middle East situation is so high,” he added.
“Exorbitantly expensive VLCC freight rates is also driving prices apart,” Shieldrop pointed out.
“VLCC freight rates are today running at 500,000 to 1,000,000 dollar a day rather than the normal 20,000 a day,” he revealed.
“This typically adds $10-20 per barrel for crude oil between the point of origin and the point of delivery some 30-50 days out in time when the crude is delivered,” he said.
“This creates a lot of confusion of what really is the price of crude oil these days. Prices are very different in time and space,” he added.
Market Levers
In a market quick take posted on its website on Tuesday, Saxo Bank noted that oil prices rose for a second day, “with Brent trading above $107 on the soon to expire November contract, while December remains just below $100”.
“President Trump’s rejection of Iran’s proposal to reopen the Strait of Hormuz is sustaining concerns about prolonged supply disruption, particularly for fuel products,” the quick take highlighted.
“At the same time, Saudi Arabia’s resumption of exports through the East-West pipeline and rising crude flows through the Strait of Hormuz should eventually help ease some of the extreme physical tightness and elevated backwardation,” it added.
“However, buyers continue to face prohibitively high freight and insurance costs, keeping the refining costs elevated,” the Saxo Bank market quick take continued.
In a press gaggle at the White House on September 26, a video of which was posted on the White House YouTube channel, Trump said, “I’m rejecting their [Iran’s] deal”.
“They want to make a deal where they open the Strait immediately because they’re losing so badly … we’re winning tremendously. We have total control of the Hormuz Strait. Massive amounts of oil are coming out of the Hormuz Strait,” he added.
“They want to make a deal and I think that’s fine, I like making a deal too but … that deal would not be acceptable,” he continued.
In a televised Meet the Press interview with NBC News on Sunday, Seyed Abbas Araghchi, Foreign Minister of the Islamic Republic of Iran, outlined, when asked for his response on Trump’s rejection of Iran’s seven-day ceasefire proposal, that the seven-day plan “can bring … life back to normal in the Persian Gulf and in the Strait of Hormuz”.
“Why are they rejecting this? This is a very important question that they have to answer,” he added.
“Our proposal is very clear. We are ready to open the Strait if certain things are done by the U.S. and these certain things are not new, have not come from … space. These are our rights that we want to be respected,” he continued.
To contact the author, email